Last updated: September 28, 2026
The Phuket property market in 2026 is broader and more complex than the luxury-villa image often associated with the island.
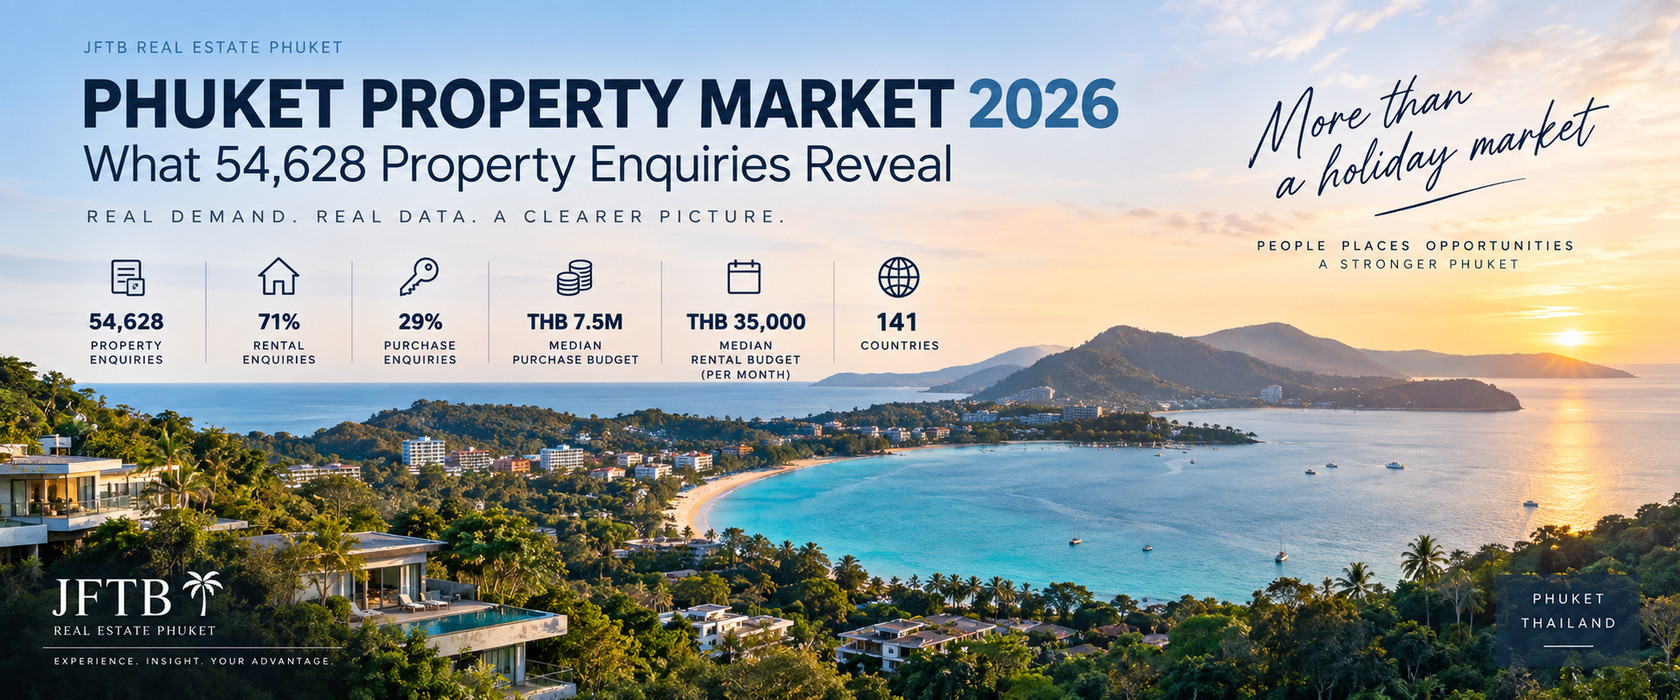
Between December 2025 and May 2026, the FazWaz property platform network recorded 54,628 buyer and tenant enquiries across Phuket, covering 1,258 projects.
Approximately 71% were rental enquiries and 29% were purchase enquiries.
The median stated purchase budget was approximately THB 7.5 million, while the median rental budget was around THB 35,000 per month.
Enquiries came from 141 countries, with approximately 62% originating from outside Thailand.
These figures provide an unusually detailed picture of what prospective buyers and tenants are actively searching for.
But they require careful interpretation.
The Phuket property market 2026 is being shaped by changing buyer budgets, stronger rental demand and significant differences between individual areas.
An enquiry is not a completed transaction. A popular area is not automatically a good investment. And high demand does not compensate for an excessive purchase price, weak ownership structure or poor resale potential.
The Phuket property market 2026 also shows why headline demand should not be confused with completed transactions or guaranteed investment performance.
The real value of the data is that it helps answer four questions:
- Where is demand concentrated?
- What property types are people searching for?
- What budgets are most common?
- How different are Phuket’s individual property markets?
Phuket Property Market 2026: Key Demand Data
| Indicator | Dec 2025–May 2026 |
|---|---|
| Total property enquiries | 54,628 |
| Rental enquiries | 39,042 |
| Purchase enquiries | 15,586 |
| Rental share | 71% |
| Purchase share | 29% |
| Median rental budget | THB 35,000/month |
| Median purchase budget | THB 7.5 million |
| International enquiry share | Approx. 62% |
| Countries represented | 141 |
| Projects represented | 1,258 |
The first important conclusion is that Phuket is not simply an ultra-luxury second-home market.
Luxury villas and branded residences are highly visible, but a large proportion of actual enquiry activity is concentrated in more accessible condominiums, apartments, houses and villas.
That matters for investors because market visibility and market depth are not the same thing.
What the 54,628 Enquiries Actually Measure
The dataset measures expressed property demand.
Prospective buyers and tenants searched listings and submitted enquiries through the FazWaz platform network and affiliated portals.
This is more meaningful than raw website traffic because submitting an enquiry represents a stronger level of interest.
However, the data does not confirm:
- whether the prospect visited the property
- whether funds were verified
- whether an offer was submitted
- whether negotiations were completed
- whether a transaction occurred
- what final price was agreed
The figures should therefore be interpreted as demand indicators rather than completed-sales statistics.
JFTB uses this type of data to understand market structure and buyer behaviour.
It should not be used to manufacture certainty about future returns.
Phuket Is Primarily a Rental-Enquiry Market
Of the 54,628 enquiries analysed, 39,042 concerned rentals.
Only 15,586 concerned purchases.
That means roughly seven enquiries out of ten were rental-related during the six-month period.
This is significant.
Phuket has evolved beyond a market used only by tourists and second-home owners. It also serves long-stay residents, expatriates, retirees, remote workers, families and international tenants.
For property investors, strong rental enquiry volume is useful.
But it should not be confused with guaranteed occupancy or guaranteed yield.
A property can sit inside a high-demand rental market and still perform poorly if:
- the rent is unrealistic
- management is weak
- maintenance is poor
- competing supply is excessive
- the property does not match tenant demand
- operating costs are too high
Demand is necessary. It is not sufficient.
The Median Rental Budget Is Around THB 35,000 per Month
The median rental budget in the dataset was approximately THB 35,000 per month.
The rental data also shows an important shift during the period. Median requested rental budgets increased from approximately THB 33,000 per month to THB 40,000 before stabilising around THB 38,000.
Rental demand is one of the clearest signals in the Phuket property market 2026, with enquiry budgets strengthening during the period.
With rental enquiries representing the majority of demand in the dataset, buyers and tenants can also compare current condos for rent in Phuket and villas for rent in Phuket.
This represents enquiry budgets rather than signed rental contracts, so it should not be interpreted as achieved market rent. However, the movement suggests that rental demand strengthened at a more durable level than the temporary March spike seen in purchase enquiries.
That tells us something important about the real structure of Phuket demand.
The centre of the rental market is not the THB 150,000–300,000 luxury-villa segment.
There is significant demand for practical residential properties at much lower monthly price points.
This includes:
- studios
- one-bedroom condominiums
- two-bedroom units
- smaller houses
- competitively priced residential properties
Higher-value villas can still perform strongly.
But they serve a smaller tenant population.
A THB 25,000 condominium and a THB 250,000 villa are effectively operating in different markets even if both are located in Phuket.
For buyers, the Phuket property market 2026 offers more choice, but also requires more careful comparison between projects, locations and price points.
One-Bedroom Properties Lead Rental Demand
One-bedroom properties represented the largest rental configuration in the enquiry dataset.
Two-bedroom and three-bedroom properties followed.
But bedroom demand changes substantially by area.
Patong, for example, naturally attracts greater demand for studios and smaller units than family-oriented residential areas.
Locations serving international schools and permanent residents can support larger homes.
Villa areas attract another type of tenant entirely.
This is why island-wide statistics should never be applied blindly to an individual property.
The correct property type depends on the micro-market and target customer.
Choeng Thale Leads Overall Enquiry Demand
The wider Choeng Thale market, including Bang Tao, Laguna and Layan, recorded approximately:
- 6,628 rental enquiries
- 3,326 purchase enquiries
- 9,954 combined enquiries
That represents roughly 18% of all Phuket enquiries in the dataset.
This level of demand reflects the area’s development into one of Phuket’s largest international residential and lifestyle hubs.
The wider area offers:
- beaches
- Laguna Phuket
- international schools
- restaurants and retail
- newer condominiums
- villa developments
- resorts
- branded residences
- premium lifestyle infrastructure
But strong demand also attracts new supply and higher land prices.
That creates an important distinction:
A high-demand area is not automatically a low-risk investment area.
Buyers still need to assess entry price, future supply, project density, management quality and resale competition.
For a closer look at this market, our Choeng Thale, Bang Tao & Layan property guide covers residential demand, villa and condominium development, lifestyle infrastructure and buyer profiles.
Premium Demand Can Be Extremely Concentrated
The data also shows how strongly premium demand can concentrate around specific projects.
Sai Taan Villas in Choeng Thale generated approximately 23% of all enquiries for properties priced above THB 30 million within the dataset.
That is a striking result.
It illustrates that high-end demand does not spread evenly across every luxury villa development.
Established reputation, location, scarcity, product quality and buyer familiarity can create a strong advantage for certain projects.
For investors, this is important because simply being labelled “luxury” does not create liquidity.
A future buyer needs a reason to choose one property over competing alternatives.
Rawai Remains a Major Residential Market
Rawai also generated substantial rental and purchase interest.
Its demand profile differs from Choeng Thale.
Rawai and nearby Nai Harn combine:
- long-term foreign residents
- retirees
- families
- lifestyle buyers
- villa tenants
- condominium renters
The area’s residential depth can be valuable because demand does not depend entirely on short-term tourism.
However, Rawai has also experienced significant villa development.
That means investors should examine the precise micro-location.
Two villas both marketed as “Rawai” may differ substantially in:
- road access
- traffic
- surroundings
- proximity to services
- construction density
- land size
- noise
- rental competition
The district name alone is not a valuation method.
For a closer look at southern Phuket, our Rawai & Nai Harn property guide covers residential demand, villas, condominiums, local lifestyle and the differences between individual micro-locations.
Patong Has a Different Demand Profile
Patong should not be analysed as if it were Bang Tao, Layan or Rawai.
The property profile is fundamentally different.
Patong enquiry activity shows greater interest in smaller units and rental properties, including studios.
That reflects its role as Phuket’s largest tourism and entertainment centre, but also its population of workers, longer-stay residents, retirees and tenants looking for convenience.
A compact foreign-freehold condominium in Patong therefore serves a completely different demand profile from a pool villa in Layan.
This illustrates a central principle of Phuket real estate:
location determines the appropriate product.
Buyers considering Patong can also read our Patong property guide for a closer look at local demand, condominium stock, rental dynamics and lifestyle factors.
Phuket Is Made Up of Multiple Micro-Markets
There is no single Phuket property market.
Choeng Thale attracts broad premium and international residential demand.
Rawai and Nai Harn combine lifestyle and long-stay demand.
Patong has substantial small-unit and rental activity.
Kamala remains relevant in the premium segment, particularly for sea-view villas and higher-value residential property. Buyers considering this area can also read our Kamala property guide for more detail on hillside locations, residential developments and local pricing dynamics.
Kata and Karon serve a different mix of tourism, second-home and residential demand, with condominiums, hillside properties and selected sea-view opportunities. Buyers comparing these areas can explore our Kata and Karon property guides for a closer look at local demand, property types and micro-location differences.
Chalong serves a more practical year-round residential market, supported by schools, marinas, healthcare access and connections to southern Phuket. Buyers considering this area can also read our Chalong property guide for more detail on villas, houses, local infrastructure and residential demand.
Si Sunthon offers a different combination of lower-density residential property, villas and comparatively lower prices.
Asking simply “Where is the best place to buy property in Phuket?” is therefore too broad.
A better question is:
Which area has the right demand for the property I am considering?
The Price Gap Between Phuket Micro-Markets Is Huge
The enquiry dataset also reveals how dramatically condominium pricing can differ between areas.
Median condominium pricing associated with enquiries was approximately:
Choeng Thale: THB 126,600 per sqm
versus
Si Sunthon: THB 32,669 per sqm
That is close to a fourfold difference.
This is one of the clearest examples of why Phuket-wide price-per-square-metre averages have limited value.
Buyers are not paying only for construction.
Prices can reflect:
- proximity to beaches
- land scarcity
- lifestyle infrastructure
- project positioning
- views
- brand
- management
- perceived future demand
- convenience
A condominium in Choeng Thale and one in Si Sunthon may both technically be Phuket condos, but economically they belong to different micro-markets.
Relevant local comparables matter more than island-wide averages.
What Are Phuket Property Buyers Actually Spending?
Across the 15,586 purchase enquiries, the median stated budget was approximately THB 7.5 million.
This is another useful reality check.
Phuket’s THB 30 million, THB 50 million and THB 100 million properties receive significant marketing attention.
But the numerical centre of purchase demand sits much lower.
That has important implications for resale.
As the purchase price rises, the potential pool of future buyers generally becomes smaller.
That does not mean expensive properties are poor investments.
Premium properties can benefit from scarcity and strong international demand.
But liquidity needs to be considered relative to price.
Condominiums Generate the Largest Share of Purchase Enquiries
Condominiums and apartments represented the largest share of purchase enquiries in the dataset.
Buyers comparing purchase demand with current inventory can explore condos for sale in Phuket and villas for sale in Phuket.
Houses and villas ranked second.
Several factors can contribute to condo demand, including:
- lower entry prices
- simpler maintenance
- central locations
- rental convenience
- foreign-freehold eligibility for qualifying units
For international buyers, the potential availability of direct foreign freehold can also make condominiums easier to understand than many villa ownership structures.
However, legal simplicity does not guarantee investment quality.
A condominium should still be assessed for:
- entry price
- foreign quota
- management
- common fees
- sinking fund
- building condition
- rental rules
- competing stock
- future resale liquidity
The THB 10–20 Million Market Has Significant Buyer Depth
The THB 10–20 million range generated meaningful enquiry volume.
That makes it an important Phuket property segment.
But it should not be labelled automatically as a “sweet spot”.
The same budget can purchase very different assets:
- larger condominiums
- premium apartments
- resale villas
- pool villas
- townhouses
- branded residences
What matters is not simply the budget band.
It is what the buyer receives for that price.
JFTB therefore treats budget data as an indicator of market depth, not as an automatic investment recommendation.
One Strong Month Does Not Create a Market Trend
March 2026 produced an unusual increase in purchase enquiry activity.
The median stated purchase budget rose to approximately THB 14 million during that month.
The increase did not continue at the same level through April and May.
That is important.
Property-market commentary often turns short-term movements into permanent narratives.
But one exceptional month does not prove a structural shift.
This is why data should be examined across periods rather than selected only when it supports a convenient story.
Phuket Demand Comes From 141 Countries
Approximately 62% of enquiries originated outside Thailand.
The dataset included demand from 141 countries.
Major international enquiry markets included the United States, United Kingdom and Russia, alongside buyers and tenants from Germany, France, Australia, the UAE and many other countries.
That diversity is one of Phuket’s structural strengths.
The island does not depend entirely on one foreign nationality.
However, international demand is influenced by:
- exchange rates
- international economic conditions
- travel connectivity
- geopolitical events
- taxation
- immigration rules
- confidence in Thailand’s property framework
Diversification reduces concentration risk.
It does not eliminate market risk.
High Enquiry Volume Does Not Equal High Investment Return
This distinction is fundamental.
A location can receive thousands of enquiries while containing overpriced properties.
Why?
Because investment performance depends on demand relative to price.
An investor who overpays in Phuket’s most popular neighbourhood may generate worse returns than someone buying a well-priced property in a smaller market.
The appropriate use of enquiry data is not:
“Buy where everyone is searching.”
It is:
“Understand where demand exists, then determine whether this particular property is correctly priced for that demand.”
Rental Demand Does Not Automatically Mean Rental Permission
High rental enquiry volume also needs legal and operational context.
Demand for short stays does not mean every condominium or villa can automatically operate as short-term holiday accommodation.
The buyer needs to separate three questions:
Is there demand?
Can this property legally and practically serve that demand?
What is the realistic net return after costs?
Management fees, common charges, maintenance, utilities, cleaning, commissions, vacancy and property condition can materially change actual profitability.
Strong gross demand is only the first part of the equation.
Resale Liquidity Starts at Purchase
The enquiry data also provides useful clues about future liquidity.
A property aimed at a broad demand segment may have a larger potential resale audience.
A highly specialised or extremely expensive property naturally has fewer potential buyers.
That does not make mainstream property automatically superior.
Scarcity can create substantial value at the luxury end.
But investors should understand who could realistically buy the asset later.
Before purchasing, ask:
Who is the next buyer?
If the answer is unclear today, it may be even harder after several years of competing development.
What the Data Means for Phuket Property Investors
The dataset supports several conclusions.
Phuket has deep rental enquiry demand.
Foreign demand is internationally diversified.
The centre of purchase demand sits well below the ultra-luxury segment.
Different areas attract different buyers and tenants.
And some premium projects capture disproportionately large shares of high-value demand.
But the dataset does not tell investors which property to buy.
A serious property decision still requires analysis of:
- ownership structure
- title and due diligence
- micro-location
- purchase price
- comparable properties
- construction quality
- management costs
- rental economics
- competing supply
- resale liquidity
Data improves the decision process.
It does not replace due diligence or judgment.
How This Analysis Differs From the Mid-Year Review 2026
JFTB also publishes a separate Phuket Property Market Mid-Year Review 2026.
The two articles intentionally serve different purposes.
This Phuket Property Market 2026 Analysis examines the behaviour of 54,628 buyers and tenants between December 2025 and May 2026.
The Mid-Year Review 2026 looks at wider H1 market conditions, including tourism, foreign condominium transfers and new condominium and villa supply.
In simple terms:
Property Market Analysis 2026 → what buyers and tenants are searching for.
Mid-Year Review 2026 → what is happening in the wider market.
Keeping these roles separate prevents short-term macro statistics and enquiry behaviour from being confused.
Frequently Asked Questions
How many Phuket property enquiries were analysed?
The dataset covered 54,628 buyer and tenant enquiries between December 2025 and May 2026.
Were most enquiries for buying or renting?
Rentals represented approximately 71%, with 39,042 enquiries.
Purchase enquiries represented approximately 29%, with 15,586 enquiries.
What was the median Phuket purchase budget?
The median stated purchase budget was approximately THB 7.5 million.
What was the median Phuket rental budget?
The median stated rental budget was approximately THB 35,000 per month.
Which area generated the most enquiries?
The wider Choeng Thale market, including Bang Tao, Laguna and Layan, generated approximately 9,954 combined sale and rental enquiries.
Which property type attracted the most purchase enquiries?
Condominiums and apartments generated the largest share of purchase enquiry activity, followed by houses and villas.
Does high demand make an area a good investment?
Not automatically.
Investment quality depends on the price paid, ownership structure, future supply, rental economics, operating costs and resale liquidity.
Is Phuket mainly a luxury market?
No.
Luxury real estate is highly visible, but the median purchase budget of approximately THB 7.5 million shows that the numerical centre of enquiry demand is considerably below Phuket’s ultra-luxury market.
Are foreign buyers important to Phuket?
Yes.
Approximately 62% of the enquiries in the dataset originated outside Thailand, with demand recorded from 141 countries.
About the Data
The figures in this analysis are based on 54,628 buyer and tenant enquiries submitted between December 2025 and May 2026 across the FazWaz property platform network.
The dataset covered 1,258 Phuket projects and included enquiries generated through FazWaz and affiliated property platforms.
This dataset provides a useful demand-side view of the Phuket property market 2026, particularly across buyer budgets, rental enquiries, preferred locations and project-level interest.
The findings were presented by Michael Kenner, Managing Director and Co-Founder of FazWaz, at the Phuket Property Exchange held at SAii Laguna Phuket on June 11, 2026.
Budgets represent amounts associated with property enquiries.
Enquiries represent expressions of interest.
They should not be interpreted as completed transactions, independently verified purchasing power or final transaction prices.
The interpretation and buyer-focused conclusions presented in this article are those of JFTB Real Estate Phuket.
Final Perspective: Phuket Is Not One Property Market
The most important conclusion from 54,628 enquiries is not that one area or property type has won.
It is that several different Phuket property markets operate simultaneously.
Rental demand differs from purchase demand.
Patong differs from Bang Tao.
Rawai differs from Layan.
A foreign-freehold condominium serves a different buyer from a leasehold villa.
A THB 7 million condominium has a different resale audience from a THB 75 million luxury villa.
The strongest property decisions therefore come from matching:
the right property
with
the right location
for
the right buyer or tenant audience
at
the right entry price.
That is where market data becomes valuable.
Not as a promise.
As a decision tool.
Speak With JFTB Real Estate Phuket
JFTB Real Estate Phuket has advised international property buyers in Phuket since 2013.
We help buyers compare villas, condominiums, investment properties and off-market opportunities based on market demand, location, ownership structure, pricing, negotiation, due diligence and future resale logic.
For current H1 market conditions, read our Phuket Property Market Mid-Year Review 2026.
For buyers preparing a transaction, see Buying Property in Thailand as a Foreigner and our Phuket Property Due Diligence guide.
If you are evaluating a specific Phuket property, JFTB can help you determine whether the property actually fits the market shown by the data before you commit.
Jean-François Martel
Founder and Senior Real Estate Advisor — JFTB Real Estate Phuket
Jean-François Martel has advised international property buyers in Phuket since 2013, with a focus on property selection, negotiation, investment analysis and due diligence coordination.